 251-217-9733
Mergers, Acquisitions and Strategic Transactions
From the first conversation about selling to the wire clearing, on either side of the deal.
What a Business Transaction Involves
A business transaction is the purchase, sale, merger, or restructuring of a company or its assets, and the legal work spans considerably more than the closing documents. It runs from the first structural conversation, through the letter of intent, due diligence, financing, and definitive agreements, to closing and the obligations that survive it.
We work both sides. Some clients are buying, some are selling, and a fair number discover mid-process that they are doing the opposite of what they intended. Industry rarely determines whether we can handle a deal. We have closed transactions in construction, transportation, services, insurance, and healthcare, for local Mobile and Baldwin County companies, for domestic businesses in international deals, and for international companies buying here.
What determines the outcome is almost always preparation, not negotiation.
What We Handle
Buy-side representation
Structuring the offer, diligence, financing documents, and the reps and warranties that decide who carries which risk.
Sell-side representation
Preparing the company, managing the data room, negotiating the LOI, and getting to close without repricing.
Letters of intent
The LOI sets more of the deal than most sellers realize. Terms conceded here are rarely recovered later.
Legal due diligence
Running it on the buy side, and surviving it on the sell side, including coordinating accountants and other advisers.
Joint ventures
Structuring partnerships between businesses, including governance, contributions, and exit mechanics.
Reorganizations and recapitalizations
Restructuring entities, equity, and debt for tax efficiency, liability, or a coming transaction.
Financing
Loan documents, security, intercreditor issues, and lender negotiation on either side.
Escrow and earnest money
Handled properly, and where appropriate we can serve as escrow agent.
Closing and post-closing
Definitive documents, closing mechanics, and the earn-outs, indemnities, and covenants that live on afterward.
Sound familiar?
How a Deal Actually Moves
01 Structure and readiness
What is being sold (stock or assets) and what that means for tax, liability, and consents. On the sell side, whether the company is ready to survive diligence.
02 Letter of intent
Price, structure, exclusivity, and the terms that quietly govern everything after. Most sellers treat the LOI as non-binding and hand away leverage in it.
03 Due diligence
The buyer looks at everything. This is where unprepared sellers get repriced, and where prepared ones hold their number.
04 Definitive agreements
Purchase agreement, disclosure schedules, reps and warranties, indemnity caps and baskets. The document that decides who pays for what nobody knew about.
05 Closing
Funding, consents, escrow, and the mechanics of transferring a business without interrupting it.
06 After closing
Earn-outs, transition services, non-competes, and the indemnity period, which is when a badly drafted agreement finally shows itself.
Who Does This Work
Robert J. Riccio
A CPA with an LL.M. in taxation from NYU. Complex tax planning, M&A, and succession (the person you want when the legal answer and the tax answer diverge, which in a transaction they routinely do).
Benjamin H. Kilborn, Jr.
Spent over a decade as in-house general counsel and has run acquisitions and development projects from the client's chair, including a seven-figure startup exit.
Jordan W Gerheim
Transaction work on both sides, including local Mobile and Baldwin County deals and cross-border transactions.
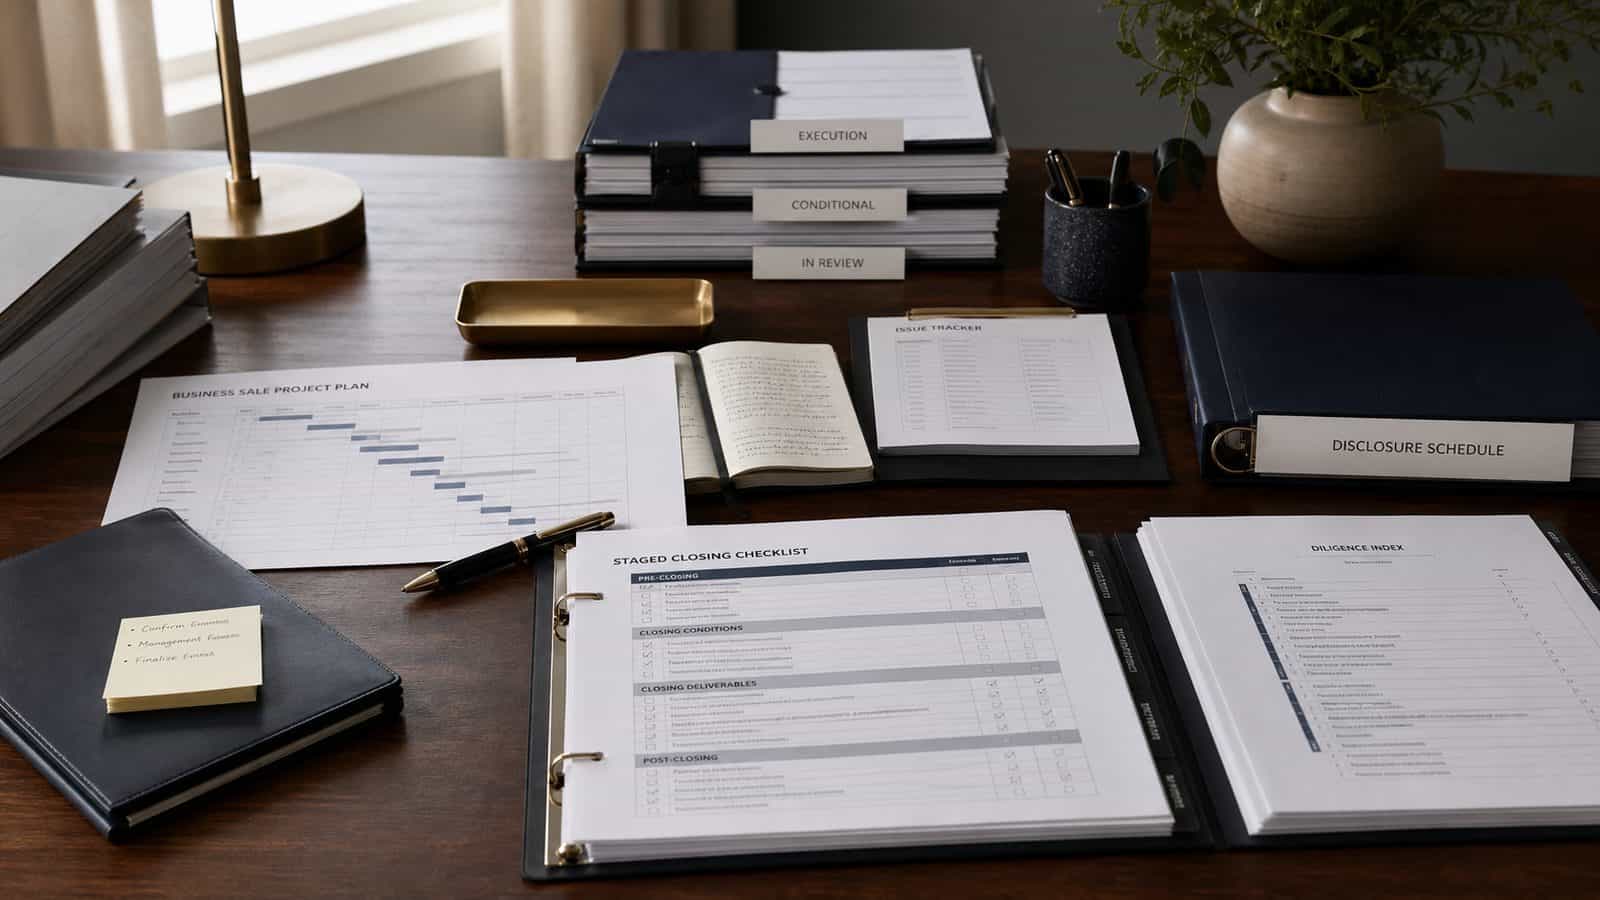
Selling Is a Project, Not an Event
Sale preparation can take up to five years. Not because the paperwork takes five years, but because the things that reduce a price take that long to fix: missing minute books, undocumented related-party arrangements, key customers with no signed contract, an ownership structure that made sense in 2015.
Buyers do not usually walk away over these. They reprice. Every unanswered question in diligence becomes a discount or an escrow, and by the time you are in diligence there is no time left to fix anything.
The owners who get the best outcomes start the conversation years before they intend to sell, often alongside a business broker and their accountant. If you think you might sell eventually, that is early enough to be worth an hour.
How Transaction Work Is Billed
Want a number for your situation?
Related Services
Frequently Asked Questions
Should I sign the letter of intent someone sent me?
Not before a lawyer reads it. An LOI is usually described as non-binding, and parts of it genuinely are, but exclusivity, confidentiality, and expense provisions frequently bind, and the commercial terms set an anchor that is very hard to move afterwards. Conceding something in an LOI and trying to recover it in the purchase agreement is one of the hardest positions in a deal.
Which is better, a stock sale or an asset sale?
It depends which side you are on, and the tax treatment usually decides it. Buyers generally prefer asset deals for the liability protection and the basis step-up; sellers generally prefer stock deals for the tax treatment and the clean break. Structure is one of the few decisions where legal and tax advice must be given together, which is why we do both.
How long does a transaction take?
A straightforward small-business sale can close in sixty to ninety days once an LOI is signed. Deals with financing, regulatory consents, multiple entities, or messy records take longer (sometimes considerably). What most reliably extends a timeline is diligence turning up something that should have been resolved beforehand.
What kills deals?
Rarely the price. Usually it is a surprise: an undisclosed liability, a key contract that turns out to be unassignable, records that cannot substantiate the numbers, or an ownership question nobody thought to check. Every one of those is findable in advance by the seller's own counsel, which is the argument for engaging one early.
Do you work with our accountant and business broker?
Yes, and we prefer it. Structure, tax, and valuation are one problem, not three, and the answers are better when the advisers are talking to each other. We work regularly with CPAs, financial planners, tax strategists, and local business brokers (brokers also bring us deals where neither party has counsel).
Related Insights
Thinking About Buying or Selling?
Book a Risk-Free Strategy Session. Bring the LOI, the offer, or just the idea. The earlier the conversation, the more it is worth.