 251-217-9733
Insurance: Coverage, Liability & Bad Faith
We spent years defending carriers. Now we use what we learned for the policyholder.
Coverage, Liability, and Bad Faith Are Three Different Fights
Insurance disputes fall into three categories that get confused constantly, and the distinction determines what you can actually recover.
A coverage dispute is an argument about whether the policy applies at all, whether the loss falls inside the grant of coverage, whether an exclusion removes it, and whether conditions were met. A liability dispute is about the underlying claim itself: who caused the loss and what it is worth. A bad-faith claim is about the insurer's conduct, whether it handled the claim reasonably, and it exists because a policy is a promise and the law treats breaking that promise as more than an ordinary breach of contract.
Most disputes start as the first, become the second, and only some of them become the third. Knowing which one you are in matters, because the evidence, the deadlines, and the potential recovery are different in each.
What We Handle
Denied and underpaid claims
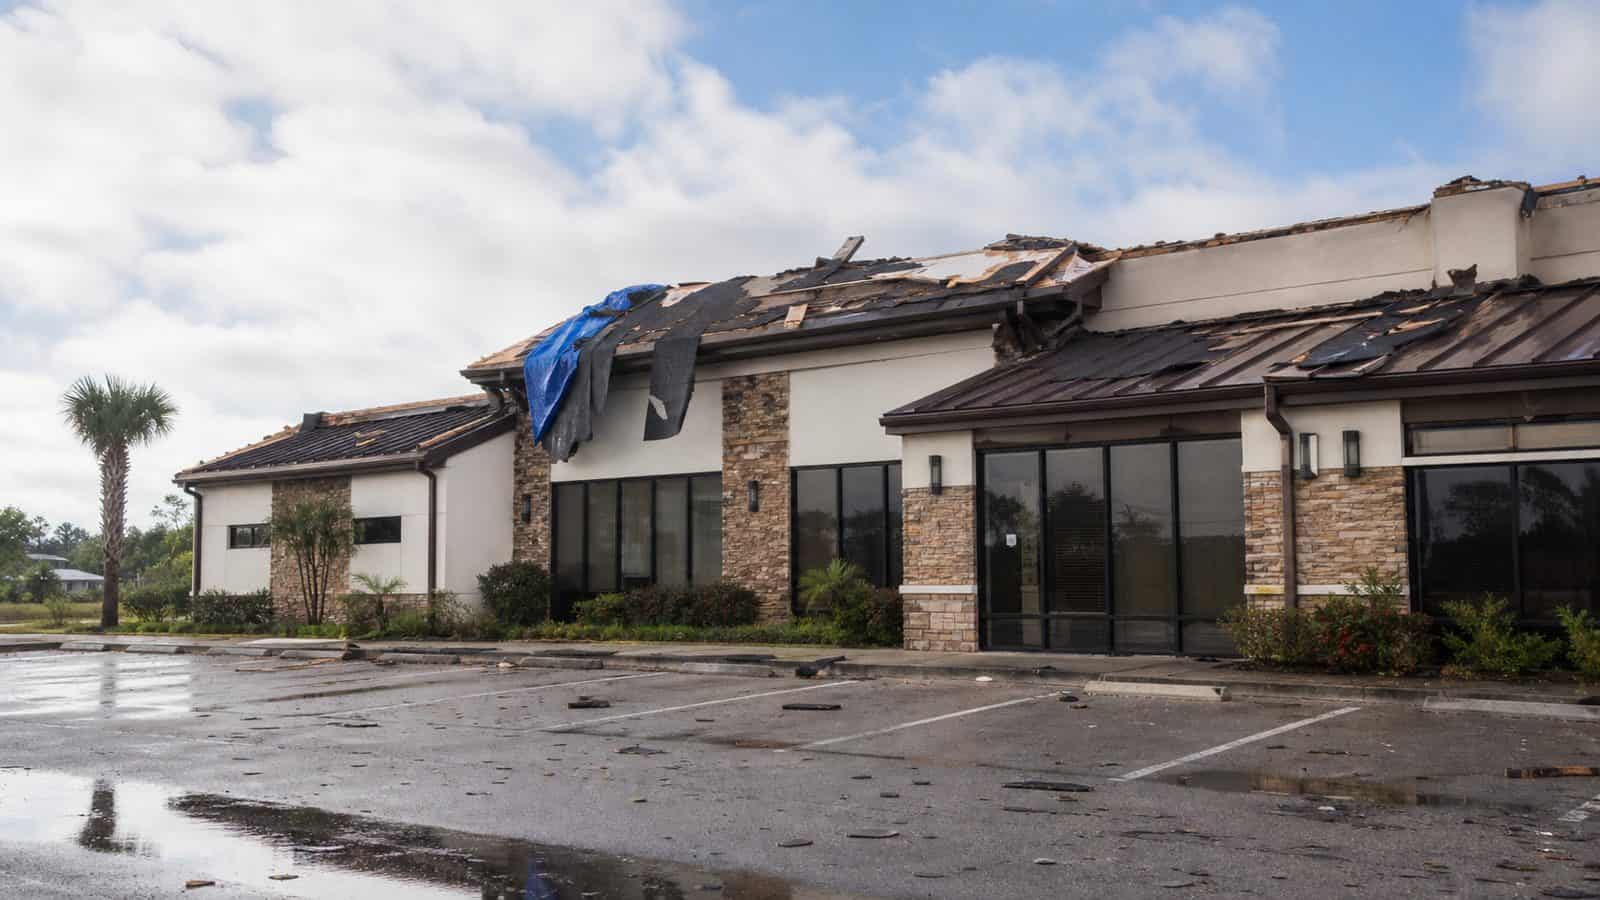
Commercial property, business interruption, liability, and specialty coverage, including coastal storm claims.
Coverage disputes
Policy interpretation, exclusions, conditions, and whether the loss you had is the loss the policy covers.
Reservation of rights
What a reservation-of-rights letter actually means, what it lets the carrier do later, and what you should do about it now.
Bad-faith actions
Claims arising from unreasonable claim handling. We have both prosecuted and defended these, which informs how we value them.
Duty to defend disputes
Where a carrier refuses to defend, or defends under conditions you did not agree to.
Monitoring insurer-appointed counsel
Where the carrier is defending you, we represent only you, and watch whether the defense being provided is actually in your interest.
Policy and renewal review
Reading what your coverage actually does before a claim, which is the only time it is cheap to find out.
Sound familiar?
Why the Defense Background Matters
Jordan Gerheim spent years as an insurance-defense litigator, retained by carriers to resolve claims. That work is where the firm came from, and it is where its founding frustration came from too. Carriers were focused on closing the claim for the least money. He kept wanting to ask how the business got there and what would have protected it.
What that background buys a policyholder now is a fairly specific kind of knowledge: how a claim is evaluated internally, which arguments a carrier takes seriously and which are posturing, what a reservation of rights is really setting up, and at what point a file stops being a negotiation and becomes a bad-faith exposure.
We still defend as well as pursue. Being credible on both sides is not a contradiction. It is why the assessment we give you at the start is worth something.
Who Does This Work
Jordan W Gerheim
Best Lawyers in America for Litigation (Insurance), 2023–present. Years of insurance-defense practice covering coverage, liability, and bad faith.
Benjamin N. Kearns
Insurance defense and bad faith, D&O liability, and business litigation, with experience representing both plaintiffs and defendants.
Duty to Defend vs Duty to Indemnify
Your insurer can owe you one of these and not the other. It is the source of more confusion than any other issue in coverage.
The obligation to provide and pay for your legal defense
The obligation to pay a covered judgment or settlement
Triggered by the allegations in the complaint
Triggered by what is actually established or agreed
Broader. It can apply even to claims that turn out not to be covered
Narrower. It applies only to what the policy genuinely covers
Decided early, often before the facts are known
Decided late, once the facts are
A carrier may defend while reserving rights on coverage
Which is the reservation-of-rights letter you received
How These Matters Are Billed
Want a number for your situation?
Related Services
Frequently Asked Questions
My claim was denied. Is that final?
No. A denial is the carrier's position, not an adjudication. Denials get reversed regularly once someone reads the policy carefully against the actual facts, and the reasons given in a denial letter are frequently narrower or weaker than they first appear. Send us the policy and the denial. That is a short review with a clear answer.
What is a reservation of rights letter?
It is the carrier saying: we will defend you for now, but we are reserving the right to argue later that this loss was never covered. It is not a denial and it is not an acceptance. It matters because it sets up a coverage dispute that will surface at the worst possible moment, usually when there is a settlement on the table. Worth understanding when it arrives rather than when it bites.
My insurer appointed a lawyer to defend me. Do I need my own?
Sometimes, and reservation-of-rights situations are the clearest case. Appointed defense counsel owes duties to you, but they are selected and paid by the carrier, and where the carrier's interests and yours diverge that creates a real tension. We represent only the insured and monitor whether the defense being provided is genuinely serving you.
What counts as bad faith in Alabama?
Broadly, it concerns whether the insurer had a legitimate or arguable reason for how it handled the claim (bad faith is not simply being wrong about coverage). The standard is demanding and the facts matter enormously, which is why the claim file, the timeline, and the internal handling are usually where these cases are decided. We have argued both sides of this and will tell you honestly where yours sits.
Is my storm damage a covered loss or an excluded defect?
That question decides who pays and it is contested in most coastal claims. Carriers have a structural incentive to characterize damage as defective construction, since defects are typically excluded. Establishing causation early (before repairs destroy the evidence) is frequently the entire case.
Related Insights
Send Us the Policy and the Letter
Book a Risk-Free Strategy Session. Send the policy, the denial, or the reservation-of-rights letter ahead, and we will have read it before we speak.